Marriage
Two financial lives become one.
Independent life insurance guidance
Understand life insurance options and compare coverage with Joe Zanni, based in Newton, NJ.
Coverage built around your life
Life changes. Plans should, too.
Life insurance is not a set-it-and-forget-it decision. A brief review after a meaningful life event can reveal whether your coverage still reflects the people, obligations, and goals that matter today.
Two financial lives become one.
A family’s future gets bigger.
A new long-term obligation begins.
More people and value may depend on you.
Your protection may not match your lifestyle.
Outstanding obligations may have changed.
A workplace benefit may be limited or temporary.
Life and policy assumptions change over time.
Coverage options
No product is automatically best. The right fit depends on how long protection is needed, the budget, the guarantees desired, and the tradeoffs you are comfortable accepting.
Coverage for a defined period, often aligned with a mortgage, income-replacement years, or another time-bound need.
May suit: Families seeking substantial coverage with a typically lower initial premium.
Consider: Coverage ends with the term unless renewed or converted, and renewal premiums may be higher.
Discuss This Option →Permanent death-benefit protection with guarantees defined in the policy and a cash-value component.
May suit: People with a long-term protection need who value predictable policy features.
Consider: Premiums are generally higher than term coverage for a comparable initial death benefit.
Discuss This Option →Permanent life insurance with interest crediting tied in part to a market-index formula, subject to caps, floors, spreads, and policy charges.
May suit: People seeking lifelong protection with flexible policy features and cash-value potential.
Consider: It is not a direct investment in an index, and illustrated non-guaranteed values may not occur.
Discuss This Option →Annuity strategies designed to help protect accumulated savings and create dependable income during retirement.
May suit: People approaching or living in retirement who want to explore guaranteed-income options.
Consider: Liquidity, surrender periods, fees, tax treatment, and guarantees vary by contract and carrier.
Discuss This Option →Typically smaller death-benefit coverage intended to help with funeral costs and other final obligations.
May suit: People seeking a focused benefit for end-of-life expenses.
Consider: Cost per dollar of coverage can be higher than some fully underwritten alternatives.
Discuss This Option →Worksite accident, critical illness, disability, hospital indemnity, cancer, and group life coverage that can help employees fill gaps in their primary health insurance.
May suit: Employers seeking to strengthen recruitment and retention while offering valuable employee-paid protection.
Consider: Product availability, eligibility, participation requirements, payroll setup, and benefit amounts vary by carrier and employer group.
Discuss This Option →Permanent coverage & cash value
Some permanent life insurance policies may build cash value. What actually happens depends on the contract, how it is funded, policy charges, crediting or dividend methods, loans, withdrawals, carrier performance, and ongoing management.
Indexed crediting uses a formula linked to an index; the policy does not directly own index securities.
Review guaranteed values separately from values based on non-guaranteed assumptions.
Both reduce policy values differently and can affect the benefit, lapse risk, and potential taxes.
Potential tax advantages depend on policy structure, status, conduct, and applicable law.
Atmospheric market imagery
This visual is decorative. It does not show policy performance, current market data, guaranteed returns, or a projection.
How it works
The conversation is built to create clarity—not urgency. Every recommendation should connect to a real need.
Start with the people, commitments, and goals behind the numbers.
Look at income, obligations, existing coverage, and the time horizon.
See balanced choices with their costs, features, and limitations explained.
Ask questions, take the time you need, and move forward only when ready.
Existing policy review
A policy review compares what you own with what has changed in your family, debt, income, or business. It is a fact-finding exercise—not an automatic recommendation to replace existing coverage.
Call About a Policy Review →A review may consider
Personal service. Flexible conversations.
Joe Zanni helps individuals and families understand coverage choices through clear explanations and a practical review of their needs.
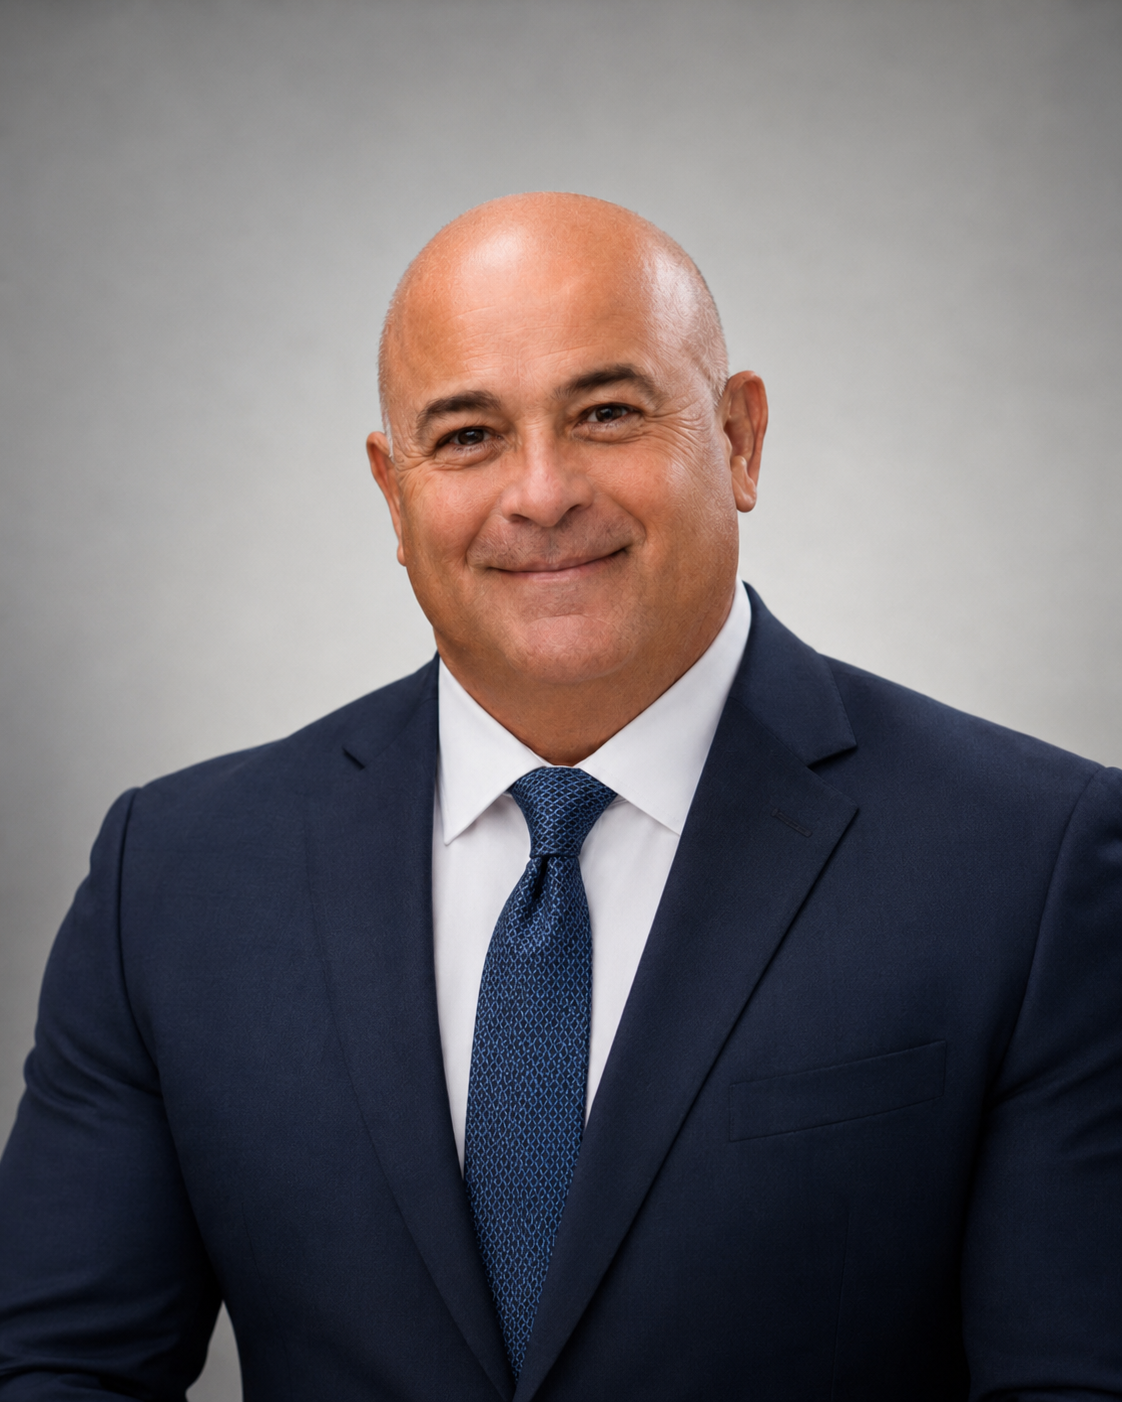
Meet your agent
JZanni Insurance
Joseph Zanni is a New Jersey insurance agent helping individuals, families, business owners, and employers understand life insurance, annuities, retirement-income strategies, and voluntary employee benefits.
Start a Conversation →Frequently asked questions
Every application and policy is different. These answers are general and are designed to help you know what to ask next.
The answer depends on the income you want to replace, debts, future goals, existing resources, and how long the need may last. An educational estimate can be a useful starting point, followed by a personalized review.
Term insurance is designed for a set period. Permanent insurance is designed to remain in force for life if policy requirements are met and may include cash value. Costs, guarantees, flexibility, and long-term goals differ by product.
Sometimes. Requirements vary by carrier, product, age, requested amount, and underwriting profile. Some applicants may qualify for accelerated or simplified underwriting, but approval is never automatic.
Common factors include age, health, tobacco use, coverage amount, policy type, term length, occupation, hobbies, and underwriting class. Carrier guidelines also vary.
Cash value is a policy component found in certain permanent life insurance products. Its growth and availability depend on the contract, funding, charges, crediting or dividend methods, and policy management.
Yes. A review can compare the original purpose with your current family, income, debt, business, beneficiaries, policy values, and expiration dates. A review does not mean replacement is recommended.
Not always, but tax treatment depends on policy status and individual circumstances. Loans reduce available cash value and death benefit; a lapse or surrender with a loan may create tax consequences. Consult a qualified tax professional.
Most term policies end without a payout when the term expires. Depending on the contract, you may have renewal or conversion options, often with deadlines and potentially higher costs.
Life insurance may be used in properly structured key-person, buy-sell, or continuity planning. Legal, tax, valuation, ownership, and beneficiary details should be coordinated with qualified professionals.
Timing varies. Applications using accelerated underwriting may move faster, while exams, records, or additional review can extend the process. Your agent can explain the likely steps for the product and carrier selected.
Request information
Answer a few questions so Joe can prepare for your conversation. After submitting, you can choose a convenient appointment time on Joe's Google Calendar.
A conversation costs nothing. There is no pressure to apply, replace a policy, or
choose a particular type of coverage.